Beyond Silos: A Coordinated Path to Investment
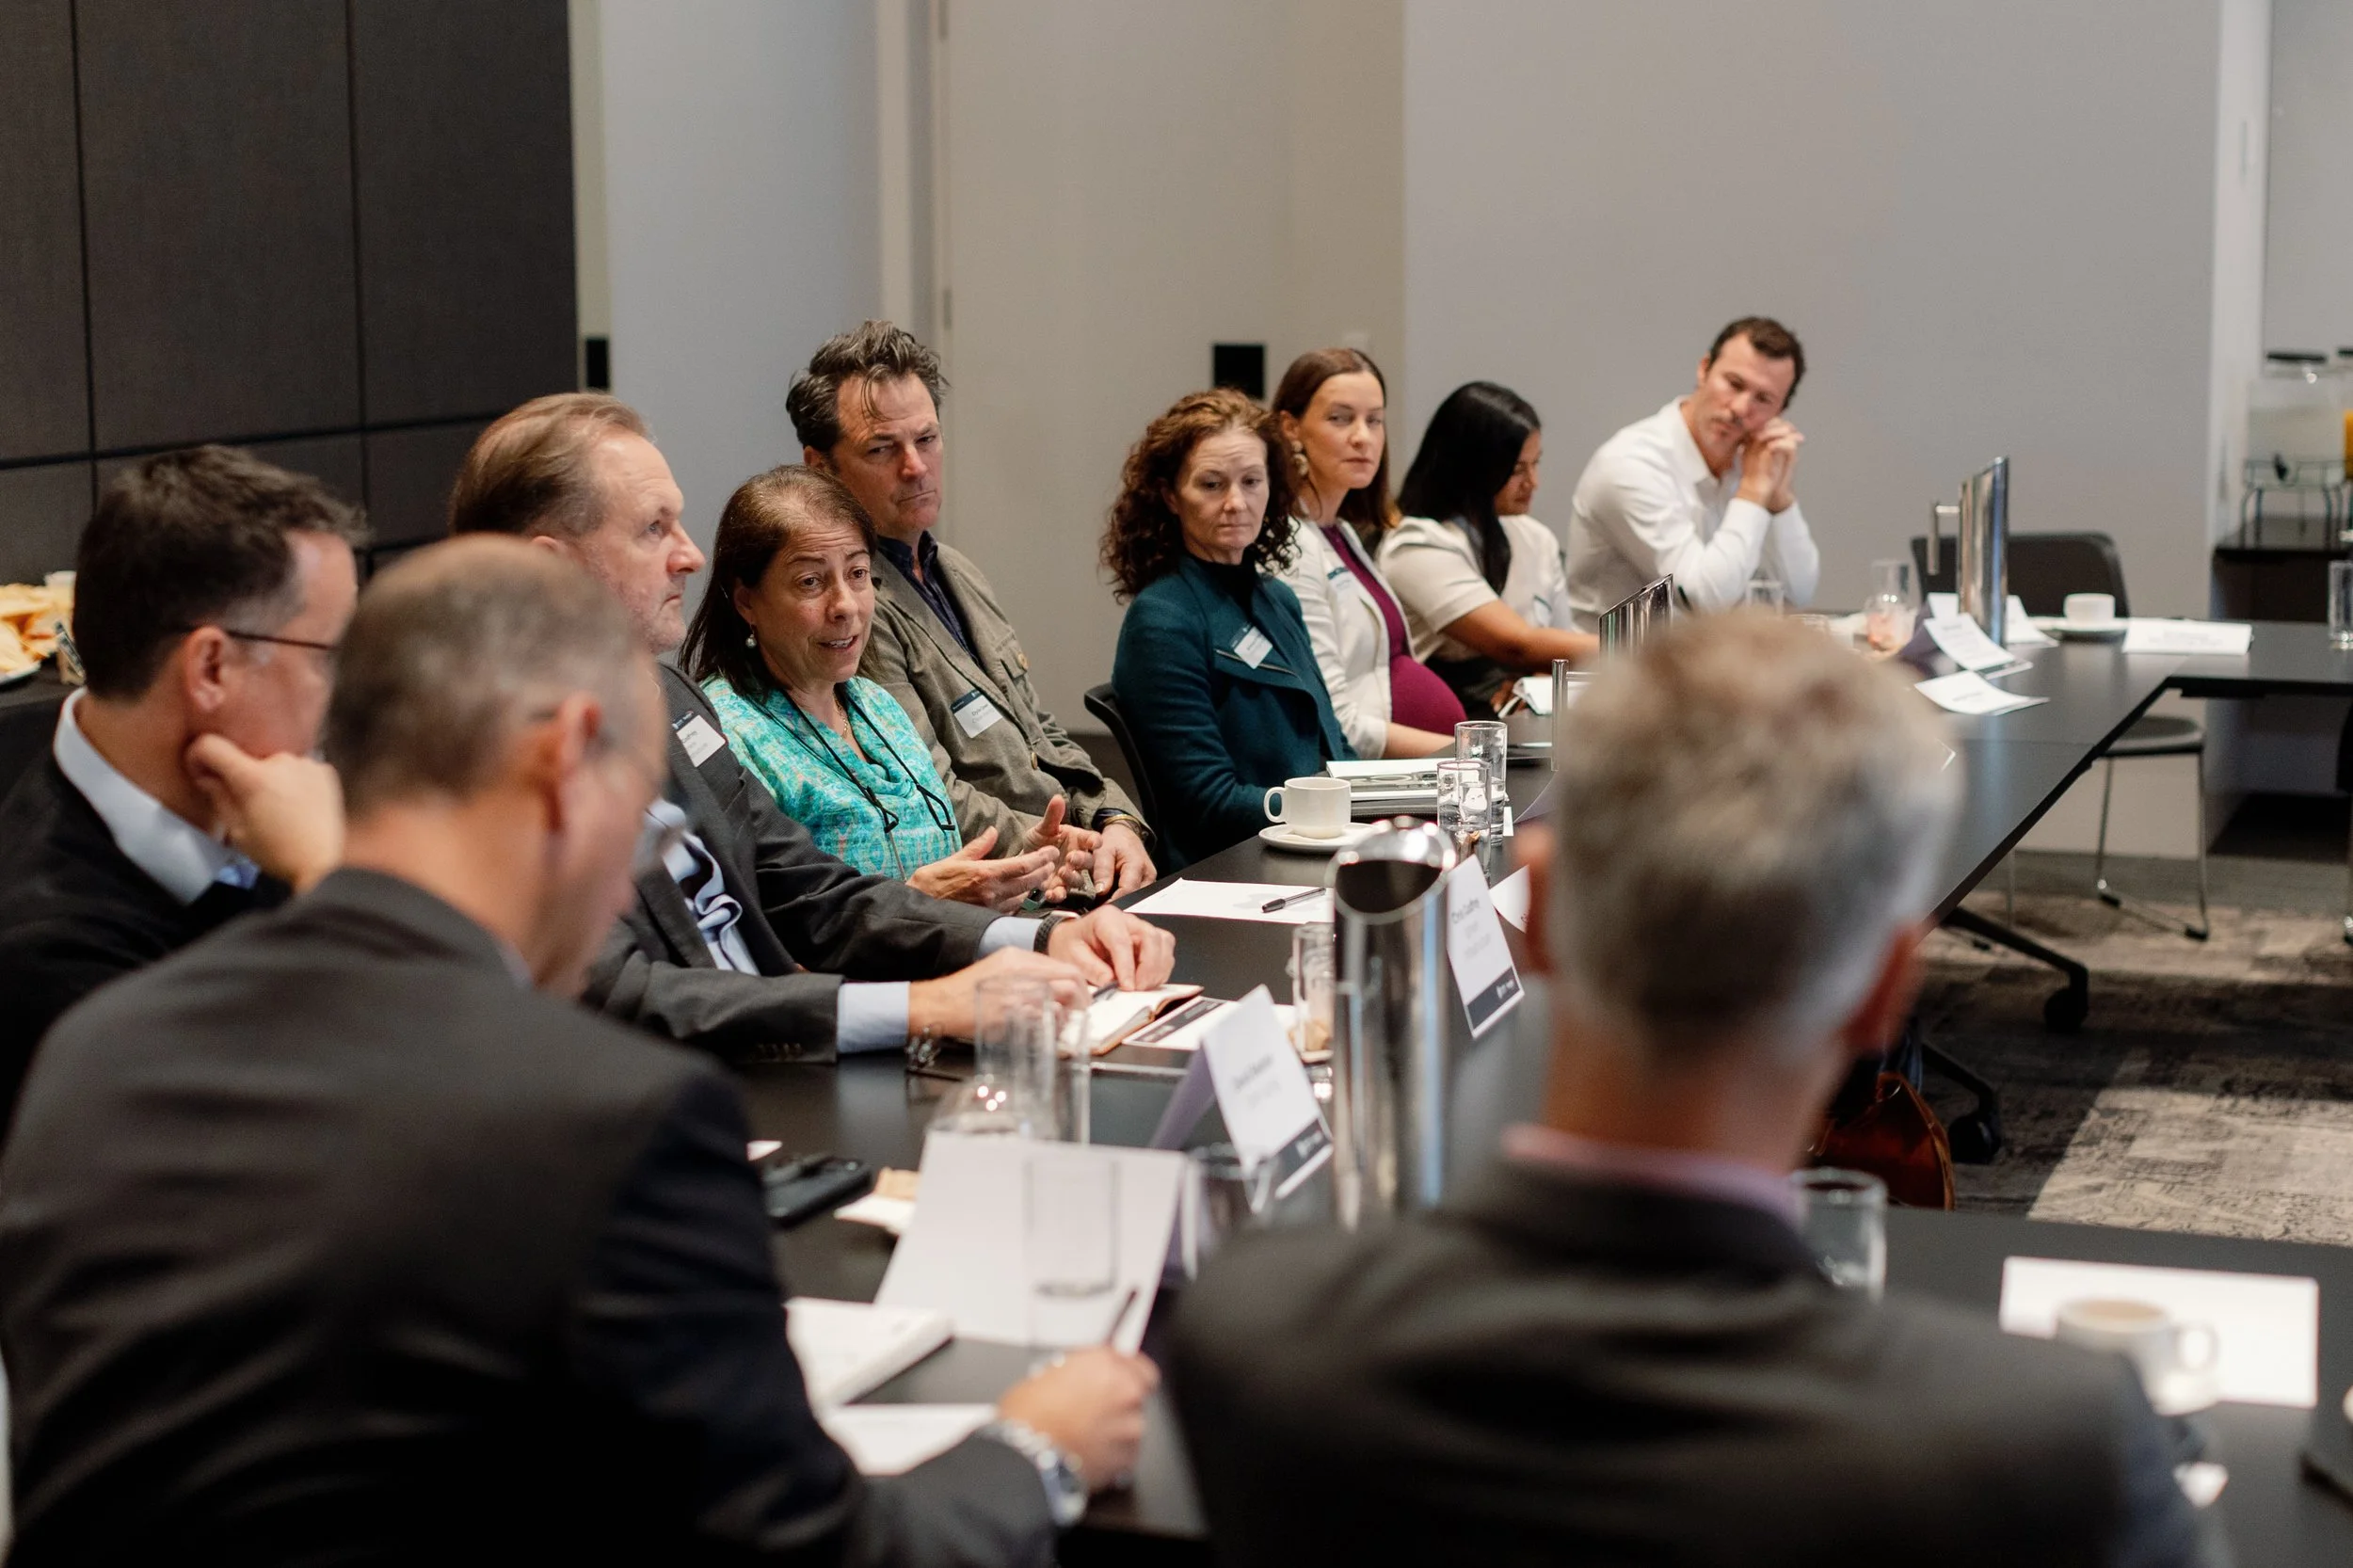
The following insights emerged from an industry roundtable that brought together leaders from across waste, water, energy, and transport to examine the barriers to delivering more integrated outcomes in Australia.
Does Australia have an environmental systems coordination problem?
Australia’s major infrastructure and environmental challenges increasingly cut across waste, water, energy, transport and land-use systems. However, planning, regulation and investment decisions are still largely made within individual sectors.
This disconnect is becoming more visible as new demands emerge. The rapid growth of data centres, for example, is creating concentrated requirements for electricity, water, land, communications and transport infrastructure. Without coordinated planning, one sector’s growth is placing pressure on other systems or competing with established community and industry needs. But coordinated planning offers the opportunity to unlock multiple value-streams for the community.
The same challenge affects resource recovery, bioenergy and other ‘waste to value’ circular economy infrastructure. Projects may create value across several sectors, but funding and decision-making in Australia remains fragmented. While there are sound technological and commercial learnings from international experience, several key barriers in Australia are causing delayed approvals, weakening investment confidence and preventing promising projects from progressing beyond the pilot stage.
Key barriers identified by industry
1. Absence of clear strategic direction
Waste and resource recovery are not consistently treated as essential infrastructure. Long-term targets are unclear, planning is often ad hoc and/or subject to highly uncertain outcomes, and existing obligations can prioritise least-cost delivery over wider decarbonisation or circular economy outcomes.
Without shared targets, organisations continue to work within separate mandates.
2. Costs and risks are concentrated, while value is shared
Integrated projects may benefit several sectors, but no single organisation captures enough value to justify taking on the risks need to support project viability. Different sectors also measure success differently, making it difficult to agree on value, allocate costs and risks, or build a strong economic and investment case.
“Theres is the potential for counterproductive trade-offs, particularly where regulators and government agencies are working towards different objectives. For example, a focus on the lowest-cost service may not always align with wider decarbonisation goals” - roundtable participant.
3. Coordination is fragmented
Industry, regulators and different levels of government often work through separate processes & timeframes – some of which can appear to support conflicting outcomes. Approval delays, political cycles, land constraints and unclear responsibilities make coordination harder.
Under uncertainty industry may also wait for coordinated government direction rather than developing a joint proposition.
4. Investment confidence remains weak
Projects involving resource recovery and circular economy outcomes need stable feedstock, credible product certification, reliable offtake, predictable revenue and consistent policy across different levels of government to secure commercial funding. Where regulation is uncertain or the value chain is incomplete, investors are less willing to commit. Policy changes after investment decisions can further damage confidence.
“Government can be both part of the solution and the main barrier. There is limited funding, narrow mandates and a lack of appetite for innovation within parts of the existing framework” - roundtable participant.
5. Trust between industry and regulators is limiting shared solutions
There are concerns about limited engagement between industry and regulators and an increasingly compliance-focused regulatory relationship.
More direct communication, clearer channels and stronger working relationships could support innovation while maintaining regulatory standards.
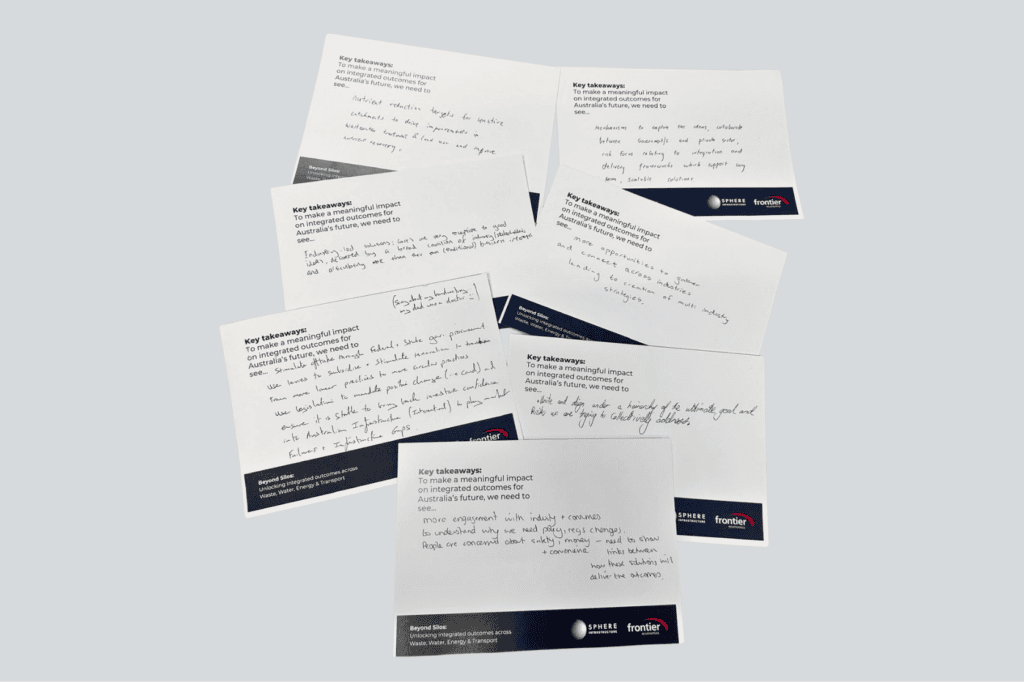
Three-part solution and action plan
1. Consider clearer cross-sector targets
Government and industry should come together to develop a small number of practical, long-term targets that connect waste, water, energy and transport outcomes.
These should be supported by common measures of value and clearer guidance on how decarbonisation, circular economy and least-cost objectives should be balanced.
“Utilities respond well to obligations. Regulatory frameworks are designed to deliver a small number of core services very well, so setting the right targets will force industry to be innovative” - roundtable participant.
Actions
Identify outcomes that require shared responsibility.
Agree common measures of economic, environmental and social value.
Consider targets for areas such as biomethane, resource recovery and circular infrastructure.
Align targets with existing regulatory obligations.
Create clear accountability for delivery and reporting.
Clear targets would provide stronger direction for industry, government and investors.
2. Build a coordinated private-sector proposition
Industry should coordinate before approaching government.
“Industry should lead and put the case to government. Government can respond quickly in a crisis, but limited resources mean industry may need to instigate change rather than wait for direction” - roundtable participant.
Operators, utilities, investors, technology providers and project partners should develop a shared, evidence-based proposition that sets out the opportunity, barriers and respective roles of industry and government.
Actions
Industry should take the lead.
Develop business cases showing who benefits, who pays and how risk is shared.
Identify planning, approval and regulatory barriers.
Separate actions industry can lead from those requiring government support.
Present a single coordinated case to government.
This would give government a clearer basis for action and show that industry is prepared to lead.
3. Determine whether a stronger collective industry voice is needed
The sector should assess whether existing associations are addressing the issues or whether stronger coordination is required.
A collective voice from either existing industry bodies, or a new one, could bring together knowledge, develop shared priorities and communicate a clearer case to government and regulators.
Actions
Establish a central point for evidence, advocacy and engagement.
Develop a shared narrative around the value of integrated projects.
Agree a focused set of policy and regulatory priorities.
The aim would not be to replace existing industry bodies, but to coordinate issues that fall between sectors.
From fragmented effort to coordinated delivery
The central challenge is not a lack of ideas or potential projects. It is the absence of a shared framework for turning cross-sector value into coordinated action.
Progress will require clearer targets, stronger private-sector coordination and a more unified approach to engagement with government and regulators.
By aligning around practical priorities, common measures of value and a coordinated industry position, the sectors involved can move beyond isolated pilots and create a clearer pathway to investment, reform and large-scale delivery.